How to calculate it
| Risk : reward | Break-even win rate |
|---|---|
| 1 : 1 | 50.0% |
| 1 : 1.5 | 40.0% |
| 1 : 2 | 33.3% |
| 1 : 3 | 25.0% |
| 1 : 4 | 20.0% |
Worked through with real numbers
A stock long at $50.00, stop at $48.50, target at $54.50. Risk is $1.50, reward is $4.50, so the plan is 1:3 and the break-even win rate is 25%.
Over 40 trades of this setup, 14 hit the target and 26 were stopped. That is a 35% win rate, comfortably above 25%:
But suppose you get nervous and close most winners early, so they average +1.9R instead of +3R:
The planned ratio was fine. The realised ratio nearly wiped the edge out. That gap between plan and execution is what a journal is for.
Where traders get it wrong
- Judging by planned ratio only. What matters is the R you actually bank, after early exits and slippage.
- Placing the stop to make the ratio look good. A stop that sits inside normal noise gets hit more, which lowers win rate by more than the ratio gained.
- Targets the market rarely reaches. A 5R target on a pair that moves 1.2 ATR a day may need a week. Check the target against ATR.
- Forgetting the spread. On a tight stop, the spread is a real slice of the risk.
Tracking it in your journal
When a trade has a take-profit, the journal shows its planned R:R, and after the close it reports Avg Risk:Reward across all trades and across winners only. TP Capture % shows how much of the distance to your target your winners actually captured, which is the number that exposes early exits.
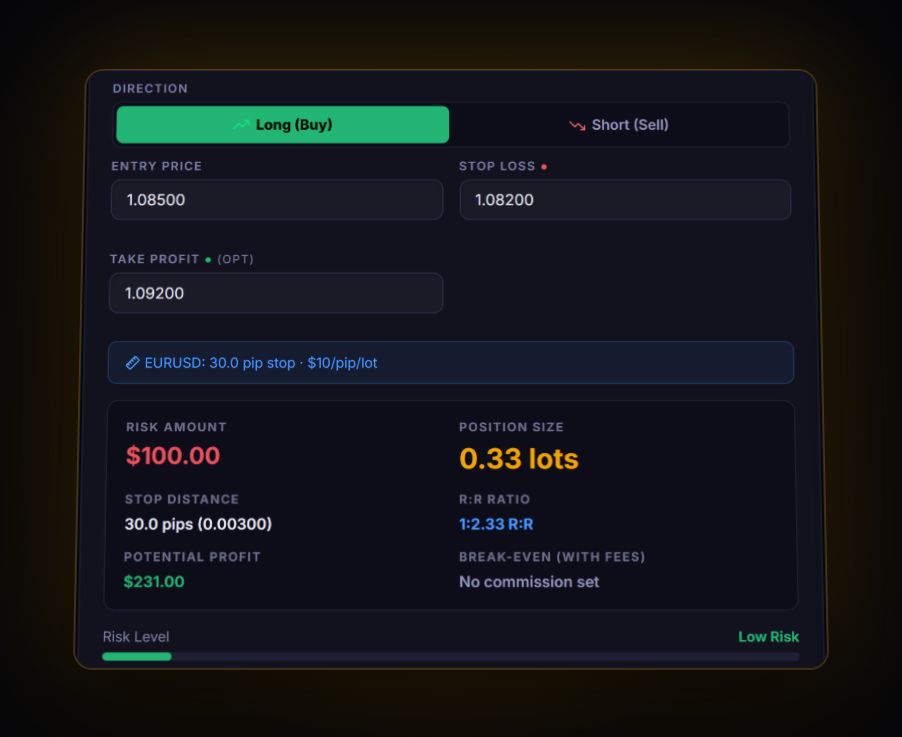
See your own Risk-Reward Ratio from real trades
Every figure on this page is more useful when it is yours. The free journal works it out from the trades you log or sync.
Start free, no card